

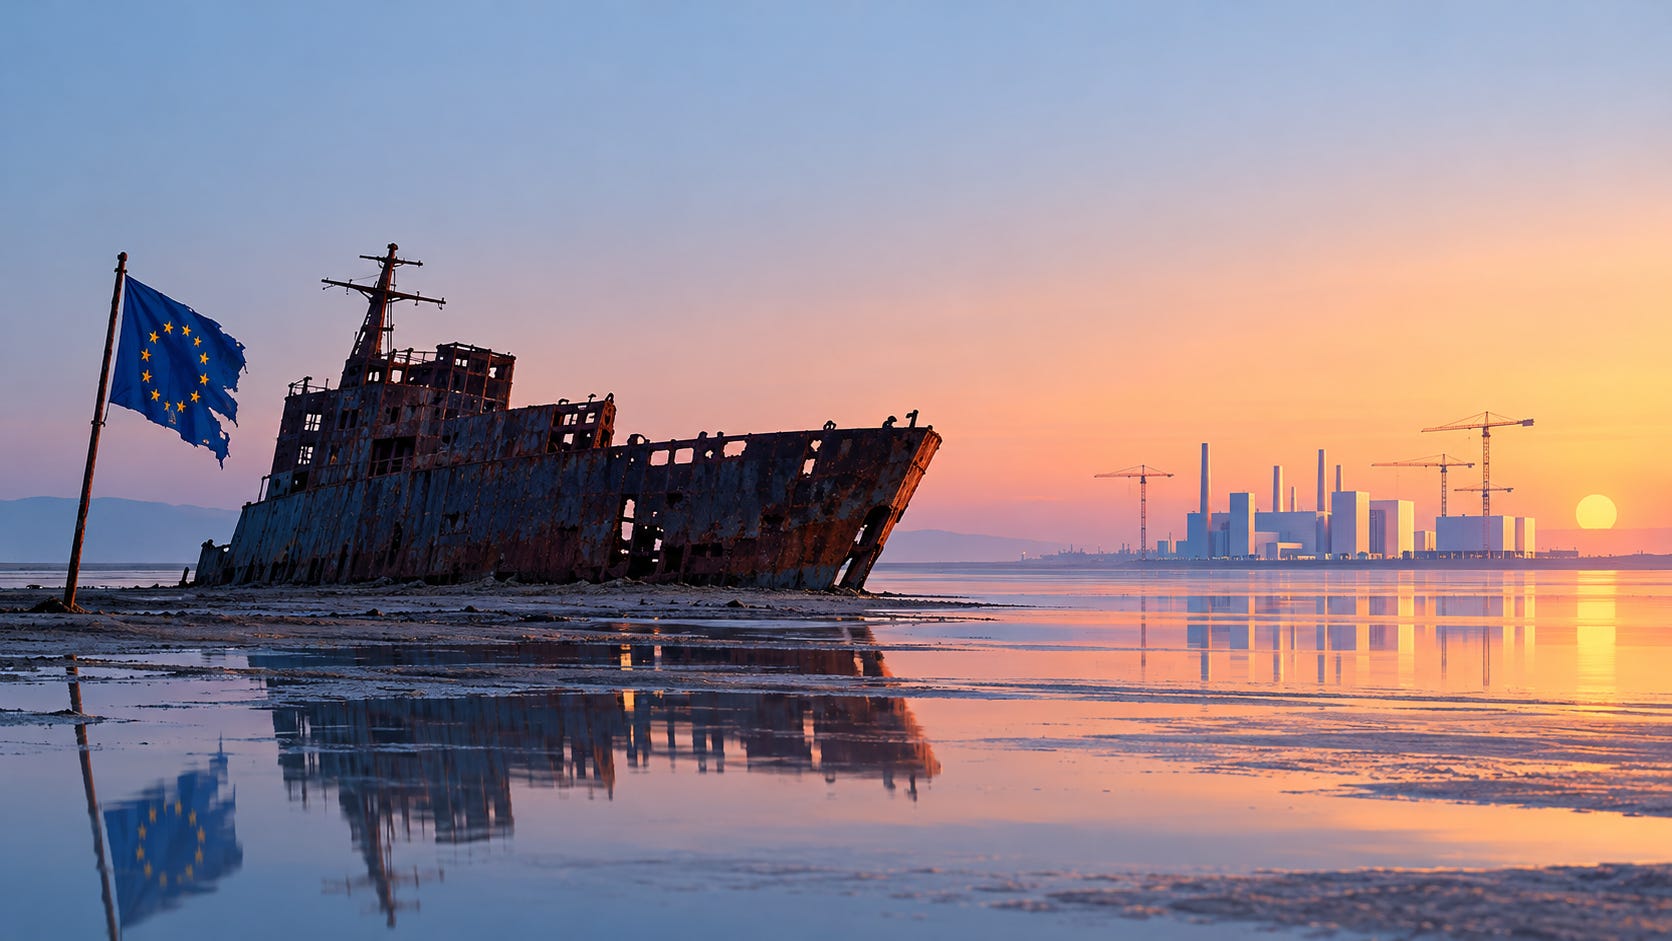
Europe loves talking about the industries of the future. AI, batteries, hydrogen, semiconductors, clean technology and quantum computing arrive accompanied by strategies, alliances, funds and photographs of important people standing in front of something reassuringly technological. Meanwhile, rather less ceremoniously and usually without ribbon cutting, parts of the industries Europe already possesses are disappearing. The chemical industry alone has lost around 15 percent of its steam-cracking capacity compared with 2021, without those losses being replaced by new investment, and Europe has not built a new steam cracker in roughly thirty years. The average one is now about 47 years old. Europe has reached the curious point where it needs a Critical Chemicals Alliance partly to identify pieces of the chemical industry that perhaps ought not to disappear.
Steel and automotive tell variations of the same story. Global overcapacity, Chinese industrial policy, high European energy costs, changing technology, weaker demand and ageing plants all play a role, so blaming every closure on Brussels would be intellectually lazy. Creative destruction also means that some factories should close. An industrial policy whose objective is keeping every old plant alive would eventually turn Europe into a rather expensive open-air museum. The relevant question is not whether this particular furnace, cracker or car factory deserves immortality, but whether Europe retains the capability to build what should replace it.
That distinction matters because Europe risks practising something rather different from creative destruction: destruction before creation. Creative destruction works when something better makes the old system obsolete. If an ageing chemical plant closes because a cleaner and more productive one has replaced it, excellent. If old automotive capacity disappears because a competitive European battery, software and electric-vehicle ecosystem has taken over, that is renewal. But if the old factory becomes uneconomic before the replacement has affordable energy, financing, customers and permission to exist, nothing particularly creative has happened. If the replacement production then appears in America, Asia or the Middle East, Europe has certainly experienced the destruction; the creative part merely occurred somewhere else.
Anyone who has survived a large IT migration should recognise the pattern. Management announces that the legacy platform will be retired, establishes an ambitious migration date and produces excellent slides explaining the architecture of the replacement. Experienced people then ask the tiresome questions. Has the new environment ever carried production load? Are all the interfaces there? Is there enough network capacity? What happens when something fails at three in the morning? Can we roll back? Only amateurs switch off the old platform before the replacement works. Europe occasionally appears to regard this as an excessively conservative approach to industrial transformation.
ASML and imec make the contradiction almost beautiful, because together they demonstrate that Europe does not suffer from some mysterious inability to understand advanced technology. Quite the opposite. Europe still possesses parts of the semiconductor ecosystem that sit at the absolute frontier of human engineering.
ASML builds machines so difficult that nobody else currently produces an equivalent to its most advanced lithography systems. Its technology is indispensable to the leading semiconductor manufacturers, its supplier network contains extraordinary European capabilities, and four customers alone accounted for more than 61 percent of ASML’s 2025 sales. Yet in September 2026 ASML executive Frank Heemskerk described the current European market with impressive economy: “We’re not selling anything at all in Europe.” Europe was not building the advanced fabs requiring the machines. The statement describes the present investment cycle rather than all of ASML’s history — the company did record some EMEA sales in 2025 — but that hardly diminishes the underlying paradox. Europe is home to perhaps the most strategically important semiconductor-equipment company on Earth while the great concentrations of leading-edge manufacturing demand sit largely elsewhere.
Imec makes the picture even more interesting. Leuven hosts one of the world’s finest semiconductor research environments, working with ASML and the leading global chip manufacturers on technologies that may define processes several generations into the future. This is genuinely extraordinary European capability, not some subsidised technology theatre. Imec also earns substantial commercial revenue. But its model depends significantly on public money: in 2024 it recognised about €239 million in Flemish grants and other publicly funded projects, including roughly €135 million drawn from its Flemish structural grant. Its NanoIC pilot line represents investment on an entirely different scale, with European, national and regional public institutions providing a very large share of the billions needed to create infrastructure that no ordinary research laboratory could afford.
There is a perfectly good economic argument for doing this. Frontier semiconductor research creates enormous spillovers, and nobody expects a university department or young company to buy a High-NA EUV machine so that researchers can experiment with what may work after 2 nanometres. Public funding of shared research infrastructure can therefore be exactly the sort of thing governments should do.
The uncomfortable question begins when the research succeeds.
Imec explicitly works with the global semiconductor ecosystem. In 2026, for example, it demonstrated a new route towards industrially viable 2D-material transistors together with ASML and TSMC, while IC-Link expanded its integration into TSMC’s design and manufacturing ecosystem. That is what a world-class research organisation should do: cooperate with the best companies available rather than erect a European fence around knowledge.
But from the perspective of European industrial efficacy, another question remains stubbornly unanswered. Europe helps finance the research environment, European engineers develop parts of the technology, ASML builds the indispensable machine, and then much of the commercial manufacturing that turns the knowledge into enormous economic and geopolitical power happens somewhere else.
The IT nerd would by now be becoming visibly uncomfortable.
To him, Europe has constructed a magnificent development environment. The developers are world class. The test laboratory is superb. The compiler is unique. The tooling costs billions and may be the best anywhere.
Production runs in somebody else’s data centre.
That is not a criticism of the developers.
It is a criticism of the architecture.
In IT, a development environment has value because there is ultimately a production system somewhere downstream. The feedback between the two is crucial. Production failures teach developers things no simulation reveals. Customers create requirements nobody anticipated. Operations people discover bottlenecks hidden from the designers. The closer the connection between development and production, the faster the whole system learns. Separate them too far and the development team may remain technically brilliant while gradually losing the feedback that comes from owning the real-world outcome.
Industrial ecosystems work much the same way. A semiconductor fab is not merely a building that consumes ASML machines. It attracts materials companies, equipment specialists, process engineers, chip designers, packaging expertise, customers and capital. Problems discovered in production travel back towards equipment manufacturers and researchers. Engineers move between companies. Suppliers learn alongside customers. One successful company creates experienced people who start the next one.
This is why the absence of European leading-edge fabs matters even if ASML and imec remain brilliant. Europe may retain critical upstream knowledge while the industrial feedback loop around that knowledge increasingly runs through Taiwan, Korea and the United States. ASML and imec prove that the creative capability still exists; they simultaneously reveal how incomplete the surrounding European production ecosystem has become.
The nerd would also ask another impolite question: what is the KPI?
If Europe spends hundreds of millions maintaining frontier research partly because semiconductor sovereignty matters, what are we measuring? Publications? Patents? Industry partnerships? Scientific prestige? Flemish employment? European startups? European fabs? European manufacturing value added? Global technological progress?
These are all legitimate objectives, but they are not the same objective.
An institution can become extraordinarily efficient at producing scientific excellence without that necessarily making Europe more industrially autonomous. That returns us directly to Part 1. Efficiency asks whether imec does excellent research with the resources available. It plainly does. Effectiveness asks whether that research produces the desired outcome. But first we need agreement about what the desired outcome actually is.
If the objective is simply advancing global semiconductor science, imec is an extraordinary success.
If the objective is strengthening Europe’s industrial semiconductor position, the answer becomes more complicated.
That is not imec’s failure. A research organisation cannot manufacture a missing industrial ecosystem around itself. Nor can ASML force customers to build fabs in Europe merely because its headquarters happen to be in Veldhoven. The surrounding conditions determine where the industrial value chain grows: electricity, water, permits, skills, capital, customers, suppliers, taxation and the willingness to place very large amounts of money at risk for decades.
And here the industrial graveyard connects with Europe’s financing problem. The continent has increasingly turned to institutions such as the EIB and European Investment Fund to fill gaps left by comparatively weak private risk markets. In 2025 the EIB Group accounted for around 30 percent of European venture-debt financing, while almost a quarter of the venture capital raised by European funds involved the EIF as an anchor investor. Those interventions can help create a market and attract private investors, but the numbers can also be read as a diagnosis of how shallow the private ecosystem remains.
Venture capital is not merely money with a more adventurous label. Good VC contains specialist judgement, networks, rapid decisions, repeated follow-on financing and a cultural acceptance that most uncertain bets may fail. European scale-ups still raise about half as much capital over their first ten years as comparable San Francisco companies, American venture investment remains six to eight times larger, and more than four out of five European scale-up deals involve a foreign lead or sole investor.
The IT nerd sees the same architectural smell here too. When a system repeatedly requires manual intervention to keep transactions flowing, eventually you stop congratulating the support team and start asking why the platform needs so much support. Public capital may be an excellent bootstrap mechanism. If it becomes a permanent substitute for a missing private risk ecosystem, Europe has not fixed the system; it has staffed the workaround.
And there is another mistake the nerd would desperately want us not to make. Having diagnosed the missing semiconductor ecosystem, Europe should resist the temptation to write a specification saying BUILD EUROPEAN TSMC HERE and then allocate enough subsidies to make the diagram come true. Complex ecosystems are not created like public buildings. They emerge from repeated interaction between customers, suppliers, capital, engineers and technologies, with numerous failures along the way. The task of government is not to predict the winning company but to create an environment in which enough serious attempts can occur that winners have a chance to emerge.
This distinction matters well beyond chips. A chemical cluster is a network. An automotive region is a network. Aerospace is a network. Shut down enough nodes and the remaining companies become less competitive even if they themselves are excellent. Engineers leave, suppliers lose volume, training becomes less attractive and the next investor finds another location where the surrounding ecosystem is already stronger. Industrial decline therefore does not arrive as a neat row of independent tombstones. Eventually the graveyard changes the economics of the land around it.
That is why Europe should not ask how many old factories it can save. It should ask what is replacing them.
There is a world of difference between protecting a forty-year-old chemical plant because it happens to employ people and ensuring that Europe retains the capability to manufacture strategically important chemicals competitively. The first freezes the incumbent. The second allows the incumbent to die provided something better can actually replace it. The same applies to steel, cars, batteries and semiconductors.
Europe’s risk is that policy increasingly accelerates the first half of creative destruction without having created the environment necessary for the second. Old industrial capacity becomes uncompetitive, while new capacity encounters energy costs, slow permitting, fragmented markets, inadequate private risk capital and a political culture that becomes nervous precisely when an investment is large enough to matter.
Then government discovers the gap and creates a programme.
The industrial battleship acquires another deck.
This does not mean the programmes are useless. Some may be essential responses to genuine market failures and foreign industrial policies. Nor does it mean Europe should imitate China or America blindly. It means that repeated emergency interventions should eventually cause us to question the architecture generating the emergencies.
ASML and imec offer perhaps the clearest reason not to despair and not to become complacent. Europe has not lost the ability to understand the future. It still produces research and engineering that the rest of the world cannot easily reproduce. What it too often lacks is the surrounding machinery that converts that intellectual advantage into a self-reinforcing European industrial ecosystem.
The nerd would probably close the incident ticket with a rather unfriendly summary:
Development works. Production is offshore. Root cause unresolved.
Before commissioning another strategy explaining what European industry will look like in 2040, perhaps that is the ticket we should fix.